Perspectives on Strategy, Governance, Cash & Turnarounds
Authored by Sanjay Lokapur, CA, CPA. Grounded in 37+ years of executive leadership, turnaround execution, family business succession, and independent directorship.
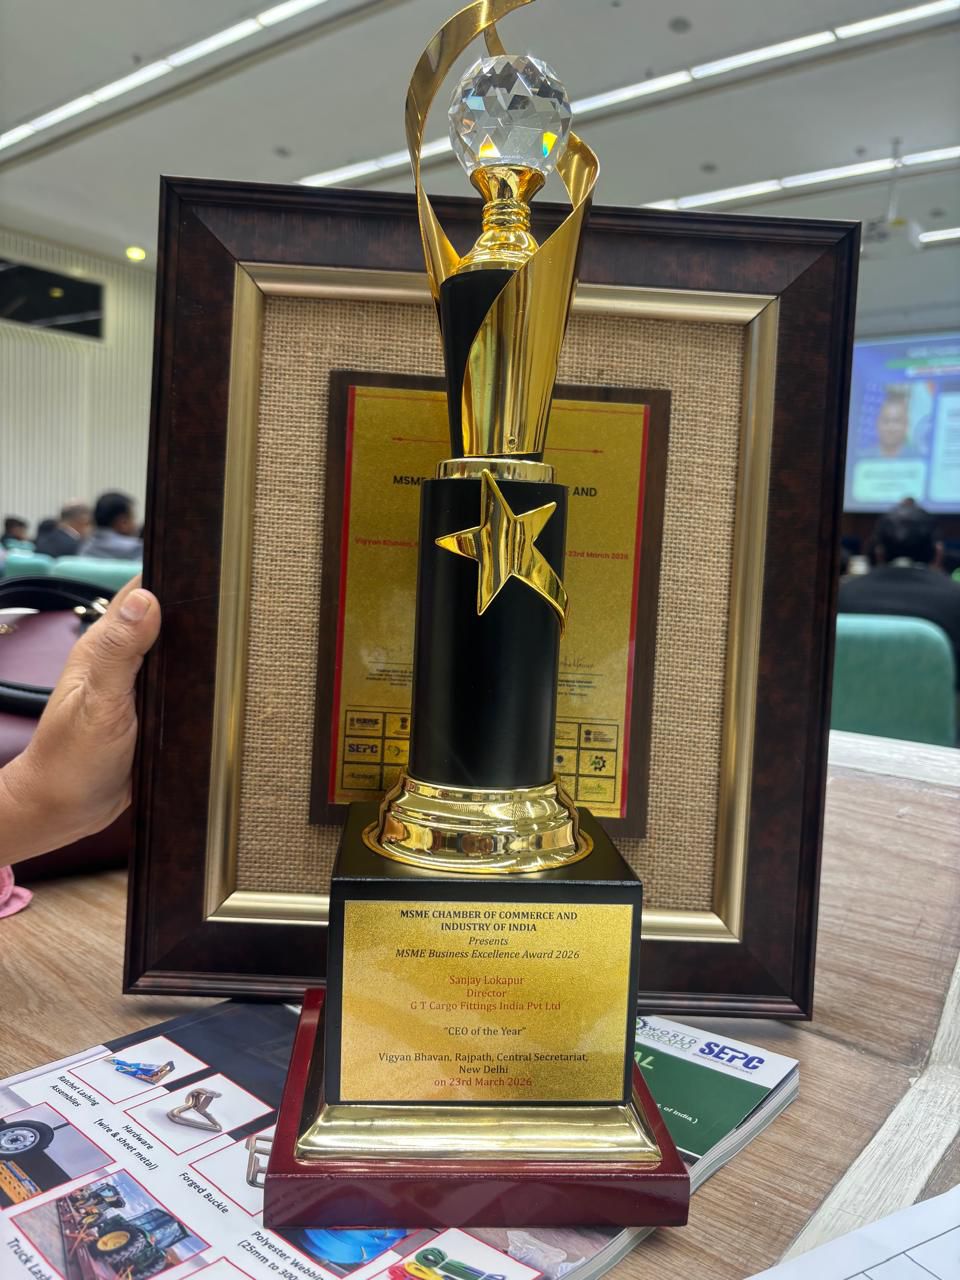
Table of Contents • Read All Chapters On This Page
4 SectionsMy Recognitions
The Growth Paradox: Why Sustainable Growth Requires a Balance Between Sales, Margins, Cash, Capital and Organisational Capacity
A White Paper for Promoters, CEOs and Boards by Sanjay Lokapur, CA, CPA. Growth should make a business larger, stronger and more valuable — not merely larger.
Executive Summary
Growth is universally celebrated. Margins are universally desired. Cash is universally needed. Yet these objectives do not always move together.
A business can increase sales and become financially weaker. It can protect margins and gradually lose market share. It can invest aggressively for growth and discover that the cash required to finance that growth is greater than the cash generated by the business. It can recruit rapidly and unintentionally damage the culture that made the organisation successful.
The management challenge is therefore not simply how to grow. It is how to grow at a rate, margin and level of complexity that the business can sustainably support.
Sustainable growth requires management to balance five interconnected variables:
Revenue growth × Margin × Cash generation × Capital efficiency × Organisational capacity
Ignoring any one of these dimensions can undermine the others.
1. Growth Is Not the Same as Progress
Revenue growth is one of the most visible measures of business success. It is also one of the easiest metrics to misunderstand.
Consider two contrasting companies:
| Metric Dimension | Company A | Company B |
|---|---|---|
| Revenue Scale | ₹100 Cr → ₹150 Cr | ₹100 Cr → ₹180 Cr |
| EBITDA Margin | 18% → 18% | 12% → 7% |
| Strategic Reality | Slower growth with stable economics | Faster growth with deteriorating economics |
Company B has grown faster, but its additional revenue may create substantially less economic value. Growth should therefore be evaluated not only by the increase in sales, but across five core financial and operational disciplines:
2. The Margin–Growth Dilemma
There is a natural temptation to protect margins. Management may say, "We will not reduce our price. We must maintain our margin." That can be rational — but if competitors are willing to operate at a lower margin, excessive focus on margin can sacrifice volume and capacity utilisation.
Margin protection can become self-defeating:
Higher price → lower competitiveness → lower volumes → under-utilised capacity → higher fixed cost per unit → further loss of competitiveness.
The opposite danger is equally serious: "Let us increase sales; we can make the margin later." This frequently leads to lower prices, higher volumes, higher receivables, higher inventory and acute cash-flow pressure.
The lesson is not that margins are unimportant. It is that margin and growth cannot be managed independently.
3. Revenue Is Not Cash
A common misconception in a growing business is: "If sales are growing, cash will take care of itself." It often does not.
Consider this simplified balance sheet comparison:
| Balance Sheet Item | Before Growth | After Growth | Enterprise Impact |
|---|---|---|---|
| Gross Sales | ₹100 Cr | ₹150 Cr | +₹50 Cr revenue expansion |
| EBITDA Margin | 15% | 12% | -3% margin contraction |
| EBITDA Profit | ₹15 Cr | ₹18 Cr | +₹3 Cr accounting profit |
| Trade Receivables | ₹15 Cr | ₹30 Cr | -₹15 Cr fresh liquidity locked |
| Inventory Stock | ₹12 Cr | ₹22 Cr | -₹10 Cr fresh cash locked |
The company has added ₹3 crore of accounting EBITDA, but substantially more money—₹25 Crore of fresh liquidity—is now locked into working capital. The accounting profit has increased; the cash available to the business has dropped significantly.
### "Profit is an accounting outcome. Cash is an operating constraint."
4. The Capex Trap
Growth frequently creates the temptation to add capacity ahead of demand. "If we are going to double the business, we should double the capacity" sounds logical, but capacity added too early or in the wrong technology can become an unbearable financial burden.
The investment cycle must follow a rigorous operating sequence:
Capex → Capacity → Utilisation → Revenue → Cash return
Before committing to major capital expenditure, management and boards should ask:
The objective should not be maximum capacity. The objective should be the right capacity at the right time.
5. Growth Can Destroy Cash Even When the Business Is Profitable
Rapid growth may require additional inventory, longer customer credit, larger receivables, additional production capacity, tooling, employees, warehouses and systems. Cash can therefore be required before the additional sales are converted into cash.
The faster the business grows, the more cash it may need to finance that growth.
6. The People–Culture Dilemma
A company that grows from 100 employees to 500 cannot assume that simply hiring another 400 people will reproduce the same performance. The organisation changes qualitatively as it becomes larger.
If management introduces too many layers, controls and new managers too quickly, the organisation can lose the entrepreneurial culture that created its success.
The company may move from "We solve problems" to "This is not my responsibility."
7. Hiring for Growth Requires More Than Headcount Planning
A growth plan that says "we need 100 additional employees" is not yet a people strategy. Management must structure human capital around four strategic questions:
Hire for the complexity you have to manage — not merely for the revenue you hope to achieve.
8. Every Growth Strategy Has a Hidden Cost
Growth consumes more than money. It consumes management attention, working capital, capital expenditure, people, systems, decision-making capacity and organisational bandwidth.
9. The Sustainable Growth Framework
A more complete definition of sustainable growth is:
Growth that increases enterprise value without disproportionately increasing financial risk, capital requirements or organisational complexity.
Measuring growth as an interconnected system requires tracking all 10 core dimensions:
| Serial | Dimension | Core Diagnostic Question | Indicative Measure |
|---|---|---|---|
| 01 | Revenue | Are we gaining sustainable market share? | Revenue growth % |
| 02 | Margin | Is growth economically attractive? | Incremental EBITDA margin % |
| 03 | Cash | Can the business finance growth? | Operating cash conversion |
| 04 | Working Capital | How much money is locked up in operations? | Cash conversion cycle (days) |
| 05 | Capital | Is incremental capital productive? | ROIC / asset utilisation |
| 06 | People | Can the organisation support growth? | Revenue per employee |
| 07 | Quality | Is growth creating operational stress? | Rejection & complaint rate |
| 08 | Culture | Are core behaviours deteriorating? | Attrition & engagement indicators |
| 09 | Customer | Is customer growth sustainable and diversified? | Customer retention & concentration |
| 10 | Risk | What unforeseen shock could derail the plan? | Key risk indicators (KRI) |
The precise metrics will vary by industry, but the principle remains constant: growth should be measured as a system, not as a single number.
10. Questions for Promoters, CEOs and Boards
Before approving high-growth expansion budgets, boards should pose these eight diagnostic questions in sequence:
Conclusion
The most dangerous growth strategy is not necessarily slow growth. It is unbalanced growth.
Excessive focus on margins can sacrifice market share. Excessive focus on sales can sacrifice margins and cash. Aggressive capex can create capacity without returns. Rapid hiring can create organisational complexity and weaken culture. Rapid expansion without adequate systems can convert a manageable business into an increasingly difficult one to manage.
Sustainable growth therefore requires continuous balancing.
Grow the revenue. Protect the economics. Fund the growth.
Allocate capital carefully. Scale the organisation without losing its character.
The real measure of successful growth is not simply how much larger the company becomes. It is whether the company becomes larger, stronger and more valuable at the same time.
Revenue Is Not Cash: Navigating the Margin–Growth Dilemma and Working Capital Traps
Why increasing sales can make a business financially weaker if margins deteriorate and cash is locked in receivables and inventory. Core insights from The Growth Paradox white paper.
Profit Is an Accounting Outcome. Cash Is an Operating Constraint.
In the boardrooms of expanding enterprises, one dangerous assumption surfaces repeatedly: "If sales are growing, cash will take care of itself."
It almost never does. As detailed in The Growth Paradox white paper, rapid revenue expansion without fiscal discipline is one of the quickest routes to enterprise vulnerability.
The Working Capital Expansion Trap
Consider what happens when a business surges from ₹100 Crore to ₹150 Crore in top-line revenue while EBITDA margin contracts from 15% to 12%:
While accounting profit shows a ₹3 Crore increase, net working capital has absorbed ₹25 Crore of fresh cash. If the business does not possess surplus liquidity or expanded bank credit lines, this growth triggers acute liquidity stress.
The Self-Defeating Margin Loop
When management chases growth without margin discipline, it enters a vicious loop:
Discounting price to win volume → Diluted margins → Extended payment terms to stay competitive → Bulging receivables → Cash flow crunch → Emergency debt at high interest.
Conversely, rigid margin defense in an aggressive competitive environment can lead to:
Higher price → Uncompetitive positioning → Idle plant capacity → Fixed overhead spread over fewer units → Surging cost per unit → Accelerated volume loss.
The Capex Discipline Formula
Capacity added ahead of verifiable demand is dead capital. Before signing off on machinery procurement or facility expansion, boards must evaluate the full sequence:
Capex → Capacity → Utilisation → Revenue → Cash return
The objective is never maximum capacity. The objective must always be the right capacity at the right time. Download the complete white paper below for the full diagnostic checklist.
Scaling Beyond Headcount: Resolving the People–Culture Dilemma in High-Growth Companies
A company growing from 100 to 500 employees cannot assume hiring more people reproduces performance. How to hire for organizational complexity rather than gross revenue.
The Shift from Problem-Solvers to Bystanders
One of the most profound observations in The Growth Paradox is the qualitative transformation of an enterprise as headcount multiplies.
A company that expands from 100 to 500 employees cannot assume that hiring 400 individuals will reproduce the founding agility and commitment. Without structured organizational architecture, the company silently shifts:
From: "We solve problems."
To: "This is not my responsibility."
When Founder-Driven Decision Making Becomes a Bottleneck
In early and mid-stage growth, the promoter's instinct and informal hallway communication drive rapid execution. But as scale doubles:
However, introducing excessive administrative layers too quickly can destroy the entrepreneurial vigor that catalyzed early success.
Hiring for Complexity vs Headcount
A growth target stating "we need to hire 150 employees this quarter" is an administrative headcount target, not a human capital strategy.
Executive management must ask:
"Hire for the complexity you have to manage — not merely for the revenue you hope to achieve."
Download Sanjay Lokapur's complete white paper for the full 10-point Sustainable Growth Framework.
The Sustainable Growth Framework: 8 Critical Questions for Promoters, CEOs and Boards
Growth should be measured as an interconnected system, not a single revenue number. The boardroom diagnostic checklist from The Growth Paradox white paper.
Beyond Single-Number Growth Metrics
In quarterly reviews, growth is customarily reported through a single metric: percentage revenue growth over the previous year. Yet, as demonstrated in The Growth Paradox, revenue growth alone provides almost zero insight into enterprise durability.
Sustainable growth is defined as:
Growth that increases enterprise value without disproportionately increasing financial risk, capital requirements or organisational complexity.
The 10 Dimensions of Sustainable Enterprise Value
A balanced board governance framework measures enterprise vitality across 10 interconnected axes:
The 8 Boardroom Questions Before Approving Expansion
Before greenlighting aggressive capital expenditure or expansion budgets, Promoters and Independent Directors should evaluate:
Download the complete original white paper by Sanjay Lokapur, CA, CPA below.

Engage with Sanjay Lokapur for Strategic Advisory
Apply these boardroom principles directly to your enterprise growth, family business succession, or corporate governance mandates.